On November 12, 2026, Yamabiko Corporation (TSE: 6250; the “Company” or “Yamabiko”), one of the core holdings of Hibiki Path Advisors SPC (“we,” “us” or “our”), announced its Q3 FY12/26 results. We would like to share our thoughts on the results and briefly revisit the Company’s distinctive growth story as we see it.
1.The Share Price and Earnings
Let’s start with the share price. The shares fell sharply on the day of the earnings announcement, down 9.2% from the previous close. By the end of Q3, the Company had already delivered around 90% of its full-year operating profit (“OP”) forecast of JPY 23bn, yet it left its full-year guidance unchanged. The market appears to have reacted negatively to what could be seen as an overly cautious stance. We don’t see a reason for pessimism here, for two reasons.
The first is OP for Q3 on a standalone basis. Judging by the share-price reaction, the market may also have been concerned about the JPY 560mn YoY decline in OP. The main driver, however, was a JPY 1.1bn increase in SG&A. What seems to have been overlooked is that gross profit actually rose by JPY 540mn, supported by strong revenue growth¹. At its Q2 results briefing, the Company had already made clear that it expected “higher sales promotion and advertising expenses, funded by tariff refunds in North America.” We therefore see this as strategic spending to help strengthen the brand going forward.
Figure 1: Q3 performance comparison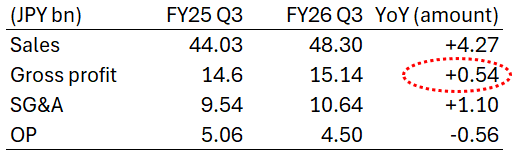
(Source: The Company’s financial results summary)
The second is growth in the Industrial Machinery segment. Again looking at Q3 alone, revenue rose 42% and segment profit rose 96% YoY—strong numbers. The financial results summary notes that “sales of our industrial machinery, generators, continued to grow significantly, particularly to major rental companies in the North American market.” More specifically, we understand that business with United Rentals, Inc. is expanding. Even we have been surprised by the scale of the impact of securing the industry’s largest player as a customer.
In late July this year, we sent the Company a letter titled “Proposal to Enhance Yamabiko’s Corporate Value”. We also made the letter public, setting out our concern that the shares remain deeply undervalued relative to intrinsic value, alongside proposals—including on capital policy—that we believe would help enhance corporate value. We hope these proposals continue to receive constructive consideration within the Company. At a share price of JPY 3,605 as of November 19, the shares still trade at a P/E of 8.9x based on the Company’s net profit forecast for the current fiscal year. To us, that valuation looks extremely cheap.
With that in mind, let’s revisit the Company’s growth story.
2.The Company’s Distinctive Growth Story
We see three key growth drivers:
1) Growth in the robotics business
2) Winning a major customer in Industrial Machinery business
3) Changes to the sales, distribution and marketing structure
1) Growth in the robotics business
The first is growth in the robotics business, whose main products are mowers and ball pickers for golf courses. The Company held a Robotics Business Briefing in August 2026 and clearly positions this business as one of its main growth drivers. In our discussions to date, management has also conveyed a fair degree of confidence in the business’s growth potential.
Video: Robotic mowers in action
The Company’s outdoor power equipment (“OPE”) segment, which includes robotics, has traditionally been strong in handheld products such as chainsaws and brushcutters. Recent technological advances, including RTK, have rapidly strengthened the competitiveness of its robotic products. Combined with the ECHO brand, we believe this has helped turn robotics into a growth driver. The Company is also sticking to its strength in serving professional users, targeting a demand base that is less exposed to passing trends such as a temporary gardening boom. As we understand it, its robots therefore do not necessarily compete head-on with those of Husqvarna and other major competitors in handheld products.
So how much could this business contribute to earnings? Based on our own estimates, we think it could reach JPY 16bn in revenue and around JPY 5bn in OP during the period covered by the MTP 2028.
Figure 2: Robotic mower sales targets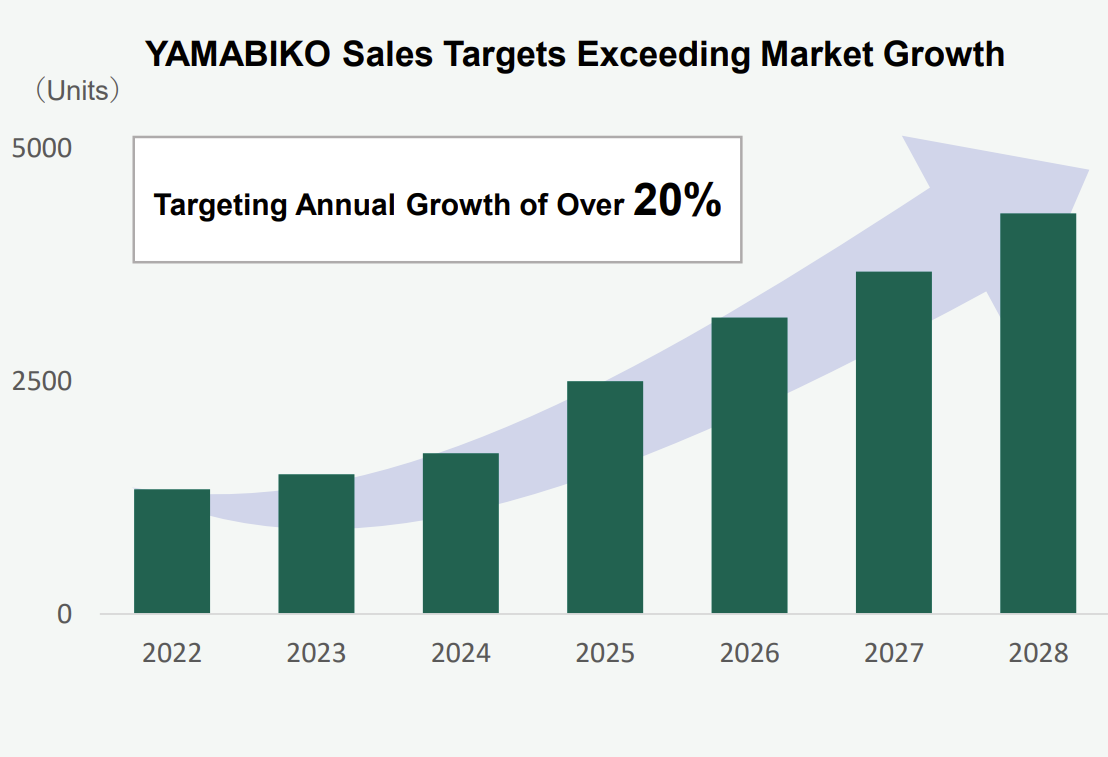
(Source: Robotics Business Briefing presentation)
On volumes, the Company has disclosed its unit sales targets in the graph above without giving precise figures. Our reading is that it points to roughly 4,000 units in FY12/28. The Robotics Business Briefing transcript (only in Japanese) suggests a price range of around JPY 3–5mn per unit. Assuming an average price at the midpoint of JPY 4mn, this would imply FY12/28 revenue of JPY 16bn. Given the business’s competitive advantage, we would expect its margin to be toward the higher end within the OPE segment. We assume an operating margin of 30%, implying OP of JPY 4.8bn.
The MTP 2028 targets OP of around JPY 27bn in FY12/28, an increase of roughly JPY 7bn from JPY 19.7bn in FY12/25. The robotics business could account for most of that increase. It is easy to see why the Company chose to hold a dedicated briefing to explain the opportunity to investors.
Views may differ on how achievable this growth is. We believe the prospects are strong, however, given that the Company can draw on the extensive distribution network of The Toro Company (ticker: TTC; “Toro”), one of the best-known companies in the US.
2) Winning a major customer in Industrial Machinery business
Next is growth in Industrial Machinery, which centers on generators for construction sites and again posted a sharp increase in revenue in Q3. Yamabiko may be best known for OPE, but Industrial Machinery segment profit grew 160% in Q2 and 96% in Q3 YoY, in each case on a standalone quarterly basis. Growth in this business is an explicit part of the current MTP 2028, and the results are already starting to show through in the numbers.
Figure 3: Growth in the Industrial Machinery segment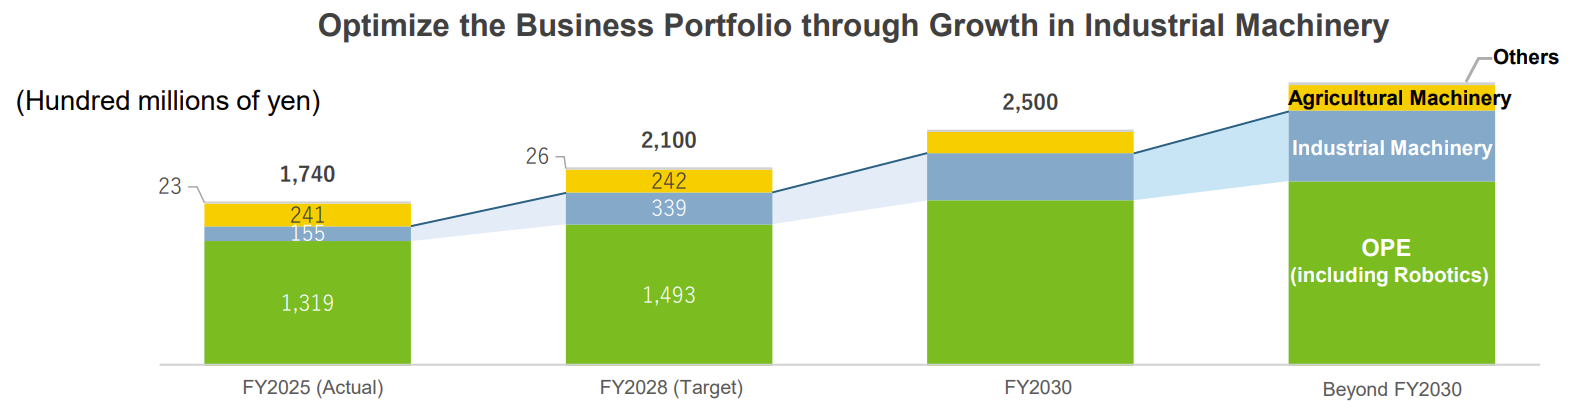
(Source: MTP 2028)
As noted earlier, we understand that business with United Rentals, Inc. (ticker: URI; “URI”) began to expand around March 2026, and that this has been a major driver of growth. URI is one of the largest rental companies in the US. In our view, the broader relationship should support steady growth in Industrial Machinery over time, rather than simply provide a one-off boost.
One point is easy to misunderstand: growth in Industrial Machinery is not necessarily dependent on the data center (“DC”) demand that has attracted so much attention recently. Among generator makers, major Japanese players Denyo and AIRMAN have increasingly come to be seen as DC-related stocks. But generators used to power data centers are what the industry calls large units. The Company’s strength lies in medium-sized units, used mainly at a wide range of construction and redevelopment sites. There have been reports that the recent US midterm elections could put the brakes on the rapid buildout of data centers. For Yamabiko, however, we don’t see this as a major cause for concern.
3) Changes to the sales, distribution and marketing structure
Finally, there are changes to the organizational structure to support business growth. Since the start of the second half of 2026, the Company has made two announcements in quick succession:
① Acquisition of Majority Equity Interest in French Distributor PPK (August 3, 2026)
② Yamabiko to Integrate Overseas Sales and Marketing Functions into Yamabiko Japan (October 1, 2026)
The first is the acquisition of a longstanding French distributor as a subsidiary to strengthen the Company’s sales structure. Yamabiko has already successfully strengthened its operations in the US by acquiring distributors. If it can apply the know-how gained there across European markets, we would expect a further improvement in its sales capabilities.
Figure 4: Disclosure on the acquisition of PPK as a subsidiary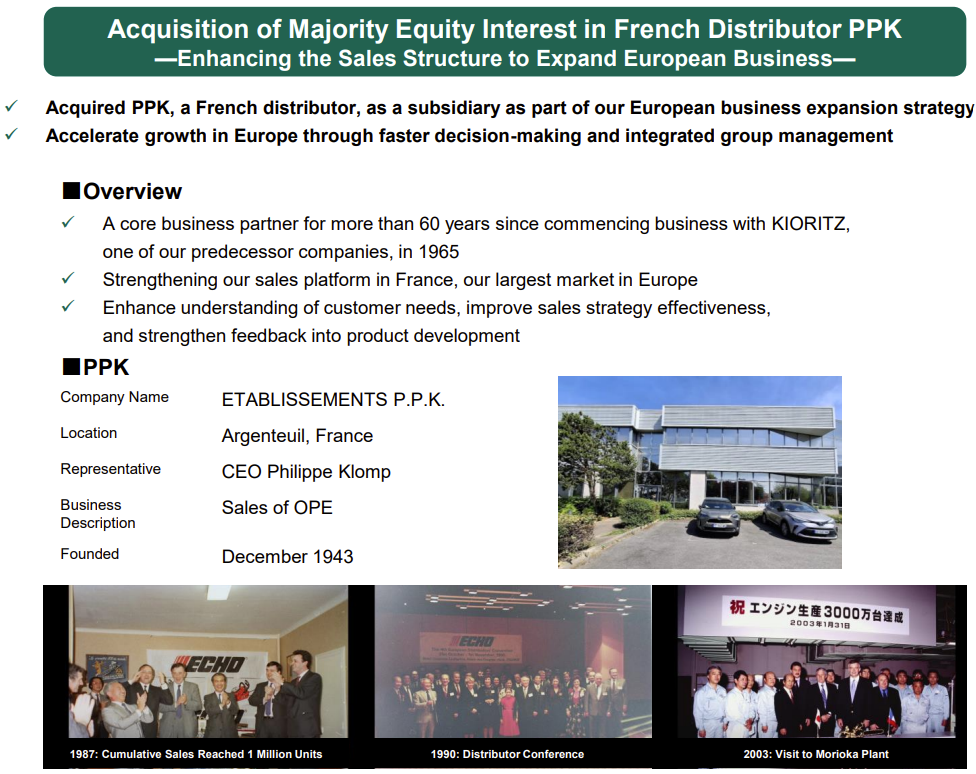
(Source: Q2 FY12/26 results presentation)
The second announcement concerns the consolidation of sales and marketing functions into Yamabiko Japan. Previously, Yamabiko Japan, a subsidiary, handled domestic sales, while the parent Yamabiko handled overseas sales and marketing. These functions will now be brought together within Yamabiko Japan. In a world where macroeconomic conditions are changing rapidly and becoming more complex, the aim appears to be to streamline the management and reporting cycle and make the PDCA cycle both more effective and faster.
We think that these steady, incremental changes to organizational and management structures, made in response to changing conditions, can create meaningful differences in competitiveness over the medium to long term when guided by clear purpose and resolve. The management team has also changed substantially in the years since Mr. Kubo became President in 2021, and we believe the governance structure needed to lead global growth is falling into place. As climate change brings more frequent natural disasters around the world, there is no shortage of challenges in finding ways for people to coexist with nature without damaging it. Against that backdrop, we feel that the scope for Yamabiko—a company that has grown by solving problems—to contribute to society is expanding considerably.
~~~~~~~~~~
We have shared our perspective as a long-term investor on the latest results, together with the Company’s distinctive growth story. A common thread runs through all of this: Yamabiko is developing growth drivers of its own that cannot be explained simply by the broader economic backdrop or short-term cycles. In that context, we believe the high equity beta—its share-price sensitivity to the wider market—that we highlighted in our letter on enhancing corporate value does not adequately reflect the underlying business. We will continue to share our views to help the market better understand that reality, while maintaining constructive dialogue with the Company!
EOD
¹ We believe this increase in revenue reflects both higher volumes and the benefit of a weaker yen.
(Previous posts)
26/Aug/2026 ― Yamabiko (ECHO): Company Introduction Materials
17/Aug/2026 ― Letter to ECHO’s parent company, Yamabiko Corporation
This post does not constitute a proposal, solicitation, marketing communication, advertisement, inducement or representation in respect of any service or product, nor does it constitute advice to buy or sell any investment product or any investment of any kind, or a recommendation to purchase or sell any investment product, make any investment, execute any transaction, or refrain from taking any other action, whether or not any terms are described. It also does not constitute an opinion regarding the merits of any particular investment or investment strategy. Any examples of strategies or transactions are provided solely for illustrative purposes and do not indicate any past or future strategy or performance, nor do they indicate the likelihood of success of any particular strategy. This post does not constitute investment, financial, legal, tax, or any other advice.
This post presents our assessments, estimates, and opinions regarding the business of Yamabiko Corporation (“Yamabiko”) and Yamabiko group companies.
This post has been prepared based on publicly available information, which we have not independently verified, and is not complete, timely, or comprehensive.
Although we believe that the information contained in this post is accurate and reliable, we make no representation or warranty as to the accuracy, completeness, or reliability of such information, or of any statements or oral communications regarding Yamabiko, Yamabiko group companies, or any other companies described herein. We also assume no responsibility for any such statements or communications, including any inaccuracies or omissions therein. With respect to public companies, there may be non-public information held by such companies or their insiders that has not been disclosed by those companies. Accordingly, all information contained in this post is presented “as is,” without any warranty of any kind, and we make no express or implied representation as to the accuracy, completeness, or timeliness of such information, or the results of its use. Readers should obtain their own professional advice and make their own assessment of the relevant matters. We disclaim any obligation or liability for any loss arising from, or in connection with, the use of all or any part of the information contained in this post, including any inaccuracies or omissions therein. Any investment involves significant risks, including the risk of a complete loss of capital. Any forecasts or estimates are provided solely for illustrative purposes and should not be regarded as indicating any upper limit of potential gains or losses. We may modify all or part of this post without notice to any person, but we are under no obligation to provide any revisions, updates, additional information or materials in relation to this post, or to correct any inaccuracies.
This post may contain content or quotations from, or hyperlinks to, publicly available third-party sources of information (“Third-Party Materials”). Permission to quote Third-Party Materials in this post may not have been sought or obtained. The contents of Third-Party Materials have not been independently verified by us and do not necessarily reflect our views. The authors and/or publishers of Third-Party Materials are independent from us and may hold views that differ from ours. The inclusion of Third-Party Materials in this post does not imply that we endorse or agree with any part of the content of such Third-Party Materials, nor does it imply that the authors or publishers of such Third-Party Materials endorse or agree with the views expressed by us in relation to the relevant matters. Third-Party Materials do not constitute all relevant news reports or views expressed by third parties regarding the matters discussed herein.
We do not intend, either by ourselves or through other shareholders, to propose at a general meeting of shareholders of Yamabiko that the business or assets of Yamabiko or Yamabiko group companies be transferred to a third party or discontinued. We also have no intention of engaging in any conduct whose purpose would be to make it difficult for Yamabiko or Yamabiko group companies to continue conducting their businesses in a stable and ongoing manner.
We currently beneficially own and/or have an economic interest in securities of Yamabiko and/or Yamabiko group companies, and may continue to beneficially own or have an economic interest in such securities in the future. With respect to our investment in Yamabiko and/or Yamabiko group companies, we may, on an ongoing basis and depending on various factors — including the financial condition and strategic direction of Yamabiko and Yamabiko group companies, the results of discussions with Yamabiko and Yamabiko group companies, overall market conditions, other investment opportunities available to us, and the possibility of purchasing or selling securities of Yamabiko and Yamabiko group companies at prices at which we desire to transact — at any time, including through open-market or private transactions after we have established a position, buy, sell, cover, hedge, or otherwise change the form or substance of our investment, including securities of Yamabiko and Yamabiko group companies, in any manner permitted by applicable laws and regulations, and we expressly disclaim any obligation to notify others of any such changes. We reserve the right to take any actions we deem appropriate in relation to our investment in Yamabiko and Yamabiko group companies. Such actions may include, but are not limited to, communications with the board of directors, management, or other investors.